Investment Property
Multi-Unit Rental Mortgages in Olds, Alberta: Down Payment and Lender Rules
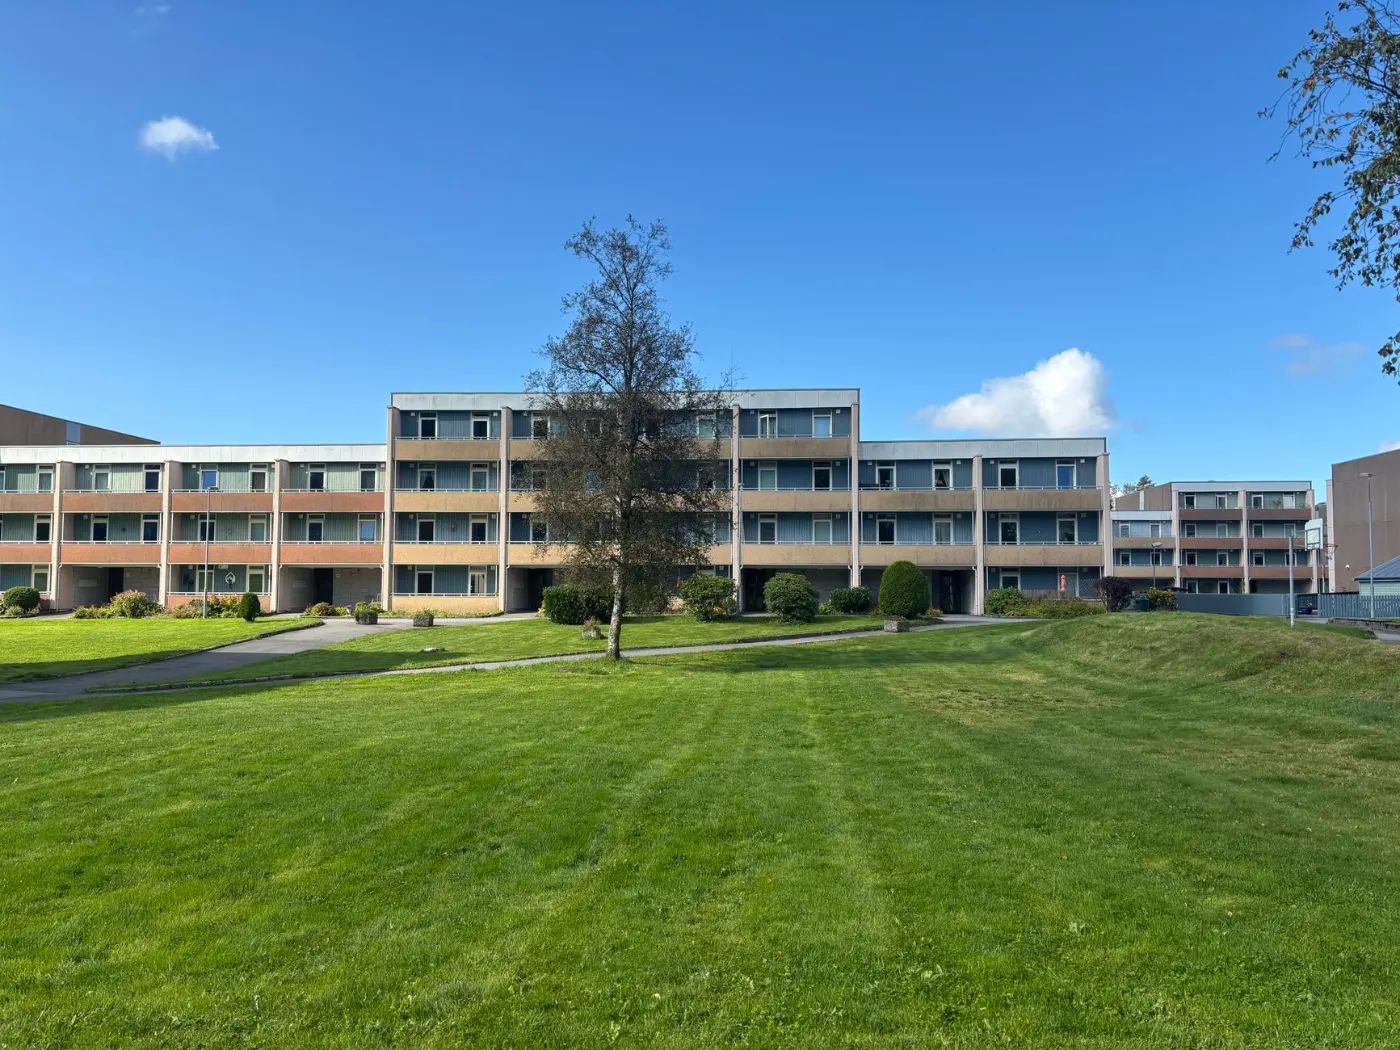
How you finance a multi-unit rental in Olds depends mostly on two things: how many units it has and whether you'll live in one of them. A duplex you live in can be bought with a small down payment, while a building you rent out entirely needs a larger one and closer scrutiny of the rent.
The local market matters too, because lenders want to know the units will rent. Below, I've set out the rental data for Olds, the financing rules for 2- to 4-unit properties, and the mistakes that cost investors the most.
What the Olds-area rental market looks like
Lenders and appraisers look at local rental demand, so start with data for Olds and similar towns rather than Calgary or Edmonton.
Vacancy in smaller Alberta towns is low
The Government of Alberta's Apartment Vacancy and Rental Cost Survey, as reported by CBC News in February 2026, found the vacancy rate in communities of 1,000 to 9,999 people fell to 3% in 2025, from 4.3% in 2024 and 14.1% in 2018. A low vacancy rate supports the rent you project, which is what a lender is testing.
Olds is adding rental housing
The Town of Olds approved a Housing Strategy on July 14, 2025, and that month the town announced groundbreaking on Silverside Pointe, a six-storey, 92-unit rental building on 65 Avenue. The town said resident surveys pointed to an urgent need for more diverse and attainable rental options. New supply also means more competition for tenants, so check current rents for the unit type you're buying.
Alberta's population growth
Alberta recorded the strongest population growth among the four largest provinces in the second quarter of 2026 and led the country in net interprovincial migration, according to the Government of Alberta's population statistics. Olds sits on the Highway 2 corridor between Calgary and Red Deer and is home to Olds College. If you're moving to Olds as well as investing, this pre-approval checklist for relocating to Olds covers the local steps.
Lenders differ in how they view rentals in smaller towns, so the lender you choose matters. My investment property mortgages for Albertans page covers how rental purchases are structured.
How to finance a multi-unit rental in Olds, step by step
Financing a duplex, triplex or fourplex follows residential rules, with a few differences from a standard purchase. Here's the order to work through it.
Step 1: Confirm the property type
The unit count, and whether you'll live there, set the path:
- 1 to 4 units, you live in one: CMHC insures up to 95% of the value on 1 or 2 units and up to 90% on 3 or 4 units, under its CMHC Purchase rules.
- 2 to 4 units, all rented: CMHC's Income Property insurance caps the loan at 80%, so you need at least 20% equity.
- 5 or more units: commercial multi-unit financing, which CMHC insures under separate programs such as MLI Select.
Step 2: Prepare your down payment and credit
On an insured purchase you'll live in, the minimum down payment is 5% of the first $500,000 and 10% of the rest for 1 or 2 units, and 10% for 3 or 4 units. A property you won't live in needs at least 20%. Rates on rental mortgages can be higher than on a home you live in, so compare the cost of every term length before you commit.
Step 3: Know how lenders count rental income
Lenders count only part of the rent when they qualify you, using either a rental offset or an add-back to your income, and each sets its own method. You'll also need to pass the stress test, at the higher of 5.25% or your contract rate plus 2%, per the Financial Consumer Agency of Canada. OSFI's 2025 clarification on rental income changed how banks classify rental mortgages for capital purposes, but OSFI says it doesn't change the B-20 rules used to qualify borrowers.
Step 4: Choose the right lender for your stage
Banks, credit unions and alternative lenders each set their own rules on rental income and on how many properties they'll finance for one borrower. Ask each lender how it treats your existing rentals before you apply, and compare the answers before you choose.
Step 5: Get pre-approved before you offer
A mortgage pre-approval in hand lets you move on a deal with confidence. Pre-approvals are typically turned around in under 24 hours.
Common mistakes Olds-area investors make
These four mistakes can limit how far a rental plan goes, and each is easier to avoid at the first purchase.
Assuming each property qualifies on its own
Each new mortgage is qualified against everything you already owe, including the mortgages on your other rentals. Rent from an existing property can help, but only the part a lender counts, and lenders differ on how they count it. Line up your next purchase with a lender whose rules suit your whole portfolio as well as the new property.
Using big-city vacancy data
Calgary or Edmonton vacancy figures don't describe Olds or Sundre. Use the provincial survey of smaller communities, the Town of Olds' housing reports and current local listings instead. CMHC's 2026 mid-year rental market update also notes that older stabilized buildings and family-sized units continue to see tighter conditions than newer, higher-priced units.
Not planning beyond the first property
If you plan to own several rentals, think about the order before you buy the first one. The lender, the down payment and how much of your income each mortgage uses all affect what you can qualify for next. If you plan to add value through renovation first, this guide to financing a BRRRR rental in Alberta covers the refinance step.
Misreading Alberta's rent increase rules
Alberta has no cap on how much rent can rise, but it does limit how often. Under the Government of Alberta's tenancy rules, rent can go up only once 365 days have passed since the last increase or the start of the tenancy, never during a fixed term, and a month-to-month tenant must get three full months' written notice. Build those limits into your cash flow projections.
Conclusion
Before you make an offer, decide whether you'll live in one of the units, since that one choice moves the down payment from 5% or 10% to 20%. Then gather your income documents and the leases and rent records for any rentals you already own, so a lender can count the rent correctly.
I work with 40+ lenders, including credit unions and alternative lenders, and can compare how each one treats your rental income. Pre-approvals are typically turned around in under 24 hours. Book a call to plan your Olds rental purchase.